By using our website, you agree to the use of cookies as described in our Cookie Policy
What Happens During a Vehicle Repossession in Neosho?
Repossession doesn't feel like a legal process. It feels like theft. One morning your truck is in the driveway. By lunch, it's gone. No knock on the door. No final warning taped to the windshield. Just an empty spot where your ride used to be. But here's the truth most people in Neosho don't know until it's too late — the lender doesn't need your permission. They don't need a court order. And if you've missed enough payments, they're already looking for your vehicle.
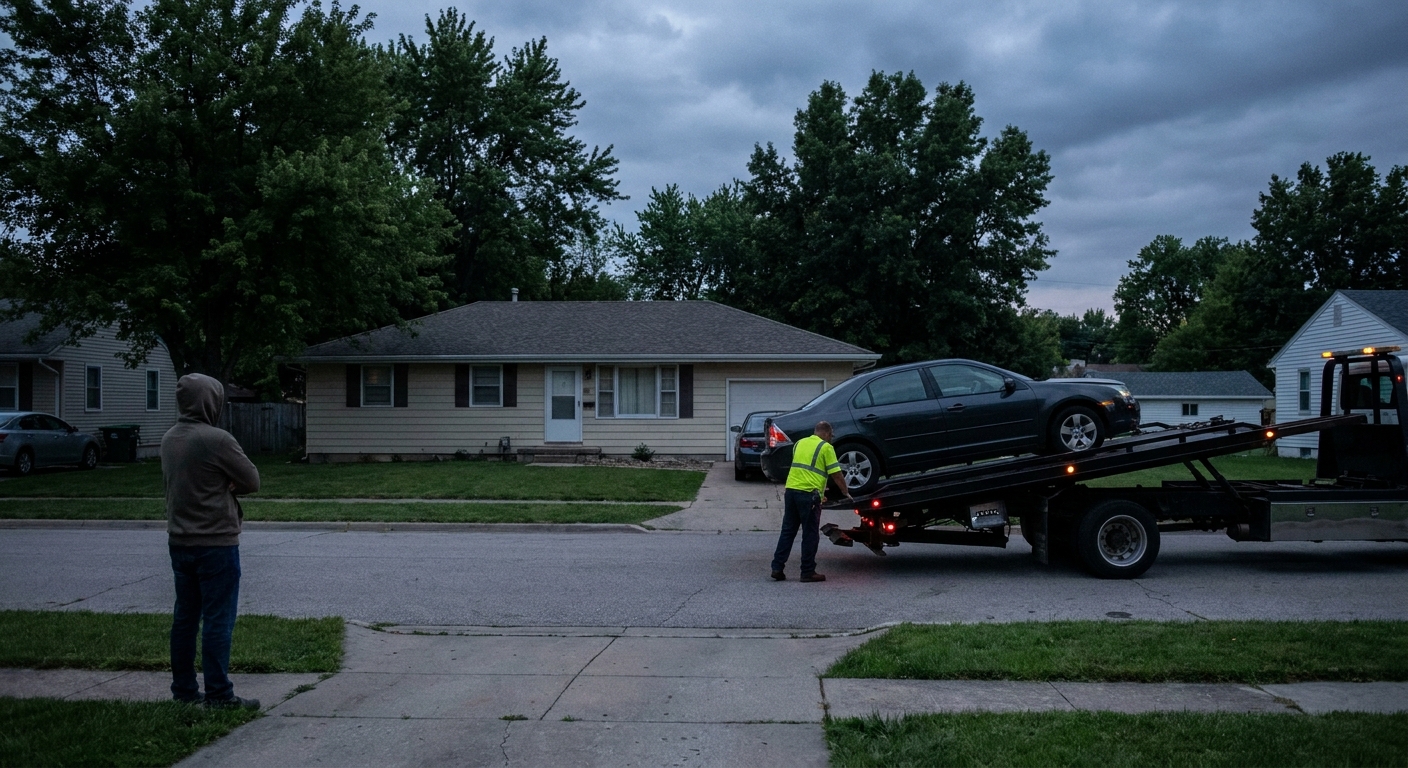
We're not here to tell you it's fair. We're here to tell you how it works. Because once the process starts, the clock moves fast. And the more you understand about what happens before, during, and after vehicle repossession, the better your chances of protecting yourself — or at least knowing what comes next.
Default Doesn't Always Mean What You Think
Most drivers assume repossession kicks in after several missed payments. Sometimes that's true. But your loan agreement might say otherwise. Some contracts allow lenders to repossess after one late payment. Others let them take the car if your insurance lapses or if you move without updating your address. The fine print matters more than the handshake you got at signing.
Missouri law gives lenders wide latitude. They can seize a vehicle without taking you to court, as long as they don't breach the peace. That means no breaking into your garage. No threats. No fights. But it also means they don't owe you a heads-up. If the agreement says they can take it, they will.
Warnings Come, But Not Always Clearly
Before repossession, most lenders will reach out. Calls. Letters. Emails. Sometimes it's automated. Sometimes it's a real person trying to work out a payment plan. If you respond and work something out, great. If you ignore them or dodge the calls, expect the tow truck.
Not every lender operates the same way. Some give you thirty days. Some give you seventy-two hours. A few don't bother with reminders at all — they just send the repo agent. The key is reading your contract and knowing when default officially starts. If you're already behind, call your lender before they call the wrecker.
The Agent Shows Up Without Notice
Repo agents work quietly. They don't announce themselves. They don't ring doorbells. They scan parking lots, check driveways, and wait for the right moment. In Neosho, that might mean your workplace parking lot at shift change. Or your apartment complex at 3 a.m. They're not breaking the law — they're just doing their job.
Once they locate the vehicle, they'll hook it up and haul it off. If you see it happening and confront them, they're required to stop and leave. But they'll come back. And next time, you might not be home.
- Agents cannot enter locked garages or fenced yards without permission
- They cannot use force, threats, or intimidation
- If you ask them to leave, they must comply — but the repo isn't canceled
- Personal items in the car must be made available to you
- Anything bolted or attached to the vehicle typically stays with it
Your Stuff Stays Yours, But You Have to Act Fast
That gym bag in the backseat? Yours. The work tools in the bed? Yours. The custom sound system you installed? That's a gray area. Missouri law requires lenders and repo companies to give you access to personal property left in the vehicle. But you need to ask, and you need to do it quickly.
Some companies will let you come to the lot. Others will mail your belongings. A few will charge a storage fee if you wait too long. Don't assume they'll hold onto your stuff indefinitely. Once the car is prepped for sale, anything left inside might disappear.
- Contact the lender or repo company immediately to arrange pickup
- Bring ID and proof that the items are yours
- Document what you retrieve in case there's a dispute
- Don't expect to get the vehicle back just because you're picking up belongings
- Aftermarket parts may be considered part of the collateral
You Can Get It Back, But It's Expensive
Redemption is the legal term for buying your car back after repossession. You pay the full loan balance, plus repo fees, storage fees, and any other costs the lender tacked on. It's not cheap. And it's not negotiable. You either pay the total or you don't get the keys.
Most people in Neosho can't come up with that kind of cash on short notice. If you can, move fast. Once the lender schedules the auction, your window closes. After the sale, redemption is off the table.
- Full loan balance must be paid, not just past-due amounts
- Repo and towing fees can add hundreds to the bill
- Storage fees accrue daily
- You have until the vehicle is sold to redeem it
- Payment terms are usually cash or certified funds
The Auction Happens Whether You Show Up or Not
If you don't redeem the vehicle, the lender will sell it. Usually at auction. Sometimes to a dealer. Missouri law requires them to notify you of the sale date and location. You're allowed to attend. You're even allowed to bid. But most people don't.
Here's the part that stings. If the car sells for less than what you owe, you're still on the hook for the difference. That's called a deficiency balance, and it's fully collectible. The lender can sue you for it, garnish your wages, or send it to collections. On the flip side, if the car sells for more than you owe, they have to give you the surplus. That almost never happens.
- Lenders must notify you of the sale in writing
- The sale must be commercially reasonable
- You are responsible for any deficiency balance
- Surplus funds, if any, must be returned to you
- You can challenge the sale if it wasn't handled properly
Breach of Peace Violations Are Rare But Real
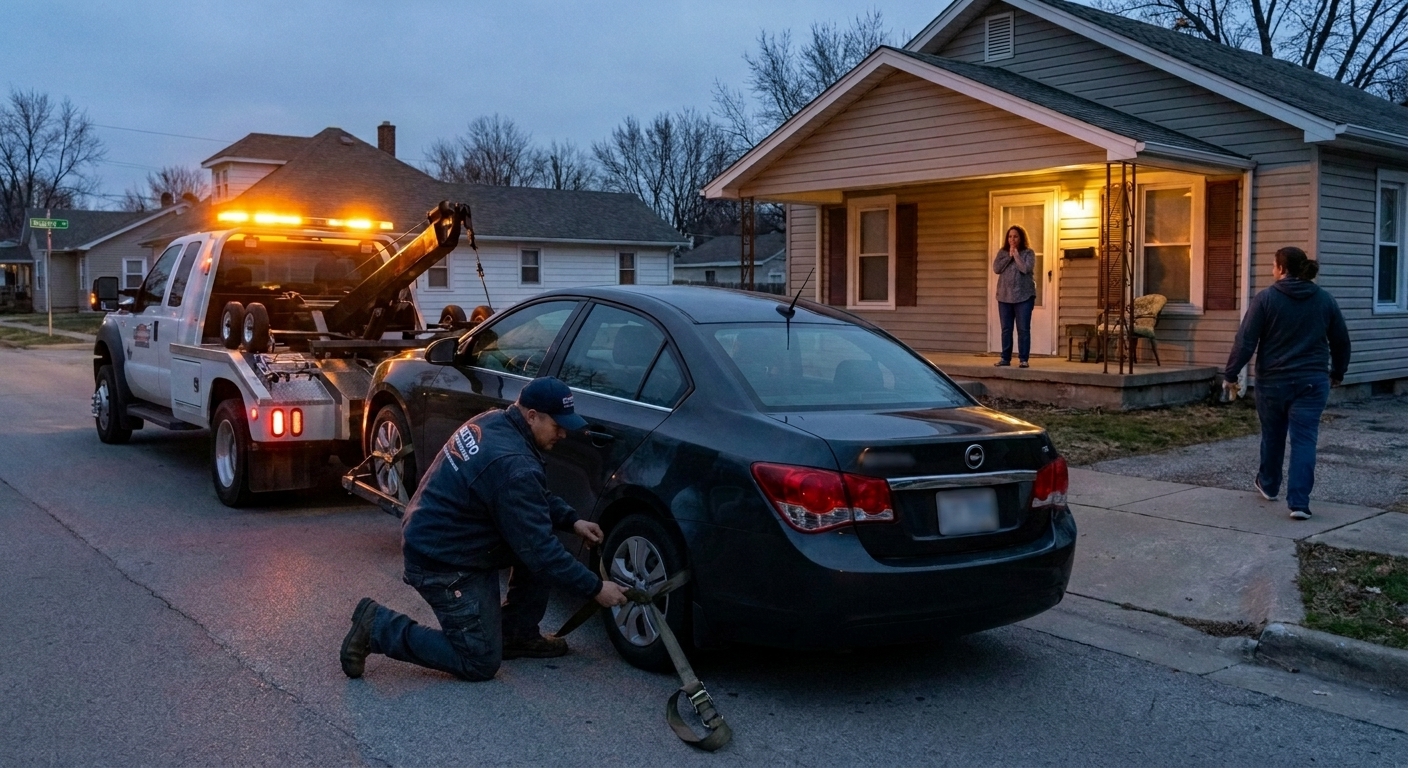
Repo agents are trained to avoid confrontation. But mistakes happen. If an agent breaks into your garage, threatens you, or ignores your request to leave, that's a breach of peace. Missouri law prohibits it. And if it happens, you may have grounds to fight the repossession or sue for damages.
Document everything. Take photos. Get witness statements. File a complaint with the Missouri Attorney General if needed. Most repo companies play by the rules, but the ones that don't should be held accountable.
Stopping Repossession Before It Starts
The best defense is staying ahead of the problem. If you know you're going to miss a payment, call your lender before the due date. Some will offer extensions. Some will restructure the loan. A few will do nothing. But asking costs you nothing, and silence guarantees repossession.
If you're already behind, see if you can negotiate a payment plan or settlement. Lenders don't want your car — they want their money. Repossession is expensive for them too. If you can show good faith and a realistic plan, many will work with you. Not all. But many.
What Repossession Does to Your Credit
Repossession wrecks your credit. It stays on your report for seven years. It tanks your score. And it makes getting another loan — car, mortgage, personal — much harder and more expensive. Future lenders see repossession as a red flag. Even if you eventually pay off the deficiency, the damage lingers.
If you're facing repossession, weigh your options carefully. Voluntary surrender might feel like giving up, but it can reduce fees and sometimes looks slightly better than forced repossession. Either way, the credit hit is severe. Plan for it.
Don't Let the Repo Define the Outcome
Losing a vehicle is a setback, not an ending. Plenty of people in Neosho have rebuilt after repossession. It takes time. It takes discipline. But it's possible. Start by addressing the deficiency balance if there is one. Then focus on rebuilding your credit. Small, consistent steps add up.
And if you're in the middle of it right now, don't ignore the lender. Don't hide. Handle it. The process is harsh, but it's not random. Know your rights. Protect your property. And keep moving forward — because sitting still only makes it worse.
We're Here When You Need a Hand
Vehicle repossession can leave you stranded and stressed, but you don’t have to face it alone. When you need fast, reliable help in Neosho, let’s get you back on the road safely and quickly. Call us at 417-609-2044 or get roadside assistance whenever you need a team that understands what you’re going through and is ready to help.
‹ Back
Recent Posts
-
What Happens During a Vehicle Repossession in Neosho?
November 2, 2026
-
How Do Dealer Vehicle Transports in Carthage Work?
October 19, 2026
-
When Do You Need a Jump Start in Neosho Instead of a Tow?
October 5, 2026
-
Can a Tow Truck in Carthage Move Your Car Without Damage?
September 21, 2026
-
When Should You Call for a Winch Out Service in Neosho?
September 7, 2026